Iron Ark PLLC · Earnout disputes
Earnout disputes for founders & sellers.
Earnouts · operating covenants · earnout accounting · acceleration
Iron Ark PLLC represents founders and sellers pursuing earnout payments after the sale of their companies. When a buyer reports a shortfall, changes how the business is run or how the numbers are counted, or simply stops paying, we pursue the earnout – in negotiation, before an independent accountant, in arbitration, or in court. We take earnout claims on a fixed fee, on contingency, or on a hybrid of the two.
How earnouts go unpaid
An earnout is part of the purchase price, paid later. It is cut in familiar ways:
- Revenue moved to the buyer's other products or business units.
- Accounting methods changed, or overhead loaded onto the acquired business.
- Sales, marketing, or staff cut that the business needed to hit its targets.
- The business integrated or rebranded until its results can't be measured.
- The founder terminated – then the payment argued away.
- Earnout statements late or vague, and books and records withheld.
- The earnout held back against indemnification claims.
The clock may already be running
Most purchase agreements give the seller a limited window to object to an earnout statement – often measured in weeks. Many send calculation disputes to an independent accountant, under its own procedure and with limits on what it can decide. Other claims – breach of operating covenants, bad faith, fraud – may belong in court or arbitration. Getting the notice and the forum right early protects the claim.
If you have received an earnout statement you disagree with, talk to us before the objection period ends.
How we pursue an earnout
Read the deal. The purchase agreement, the earnout schedule, the operating covenants, the dispute provisions, and your employment terms – read together.
Rebuild the number. The earnout as it should have been calculated, set against the buyer's statement.
Choose the path. Objection notice, accountant determination, negotiation, arbitration, or litigation – and the order they come in.
Press the claim. Senior lawyers who know how these deals are negotiated and how these cases are tried. This is the Iron Ark Method: everything that matters, nothing that doesn't.
From the boardroom to the courtroom
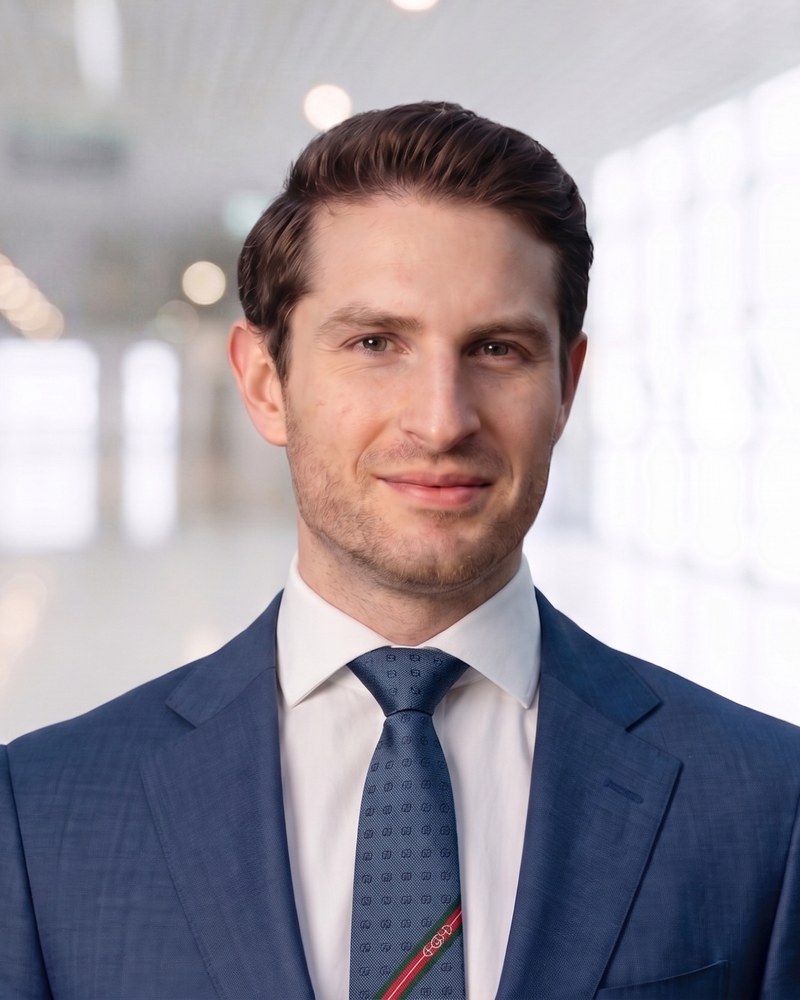
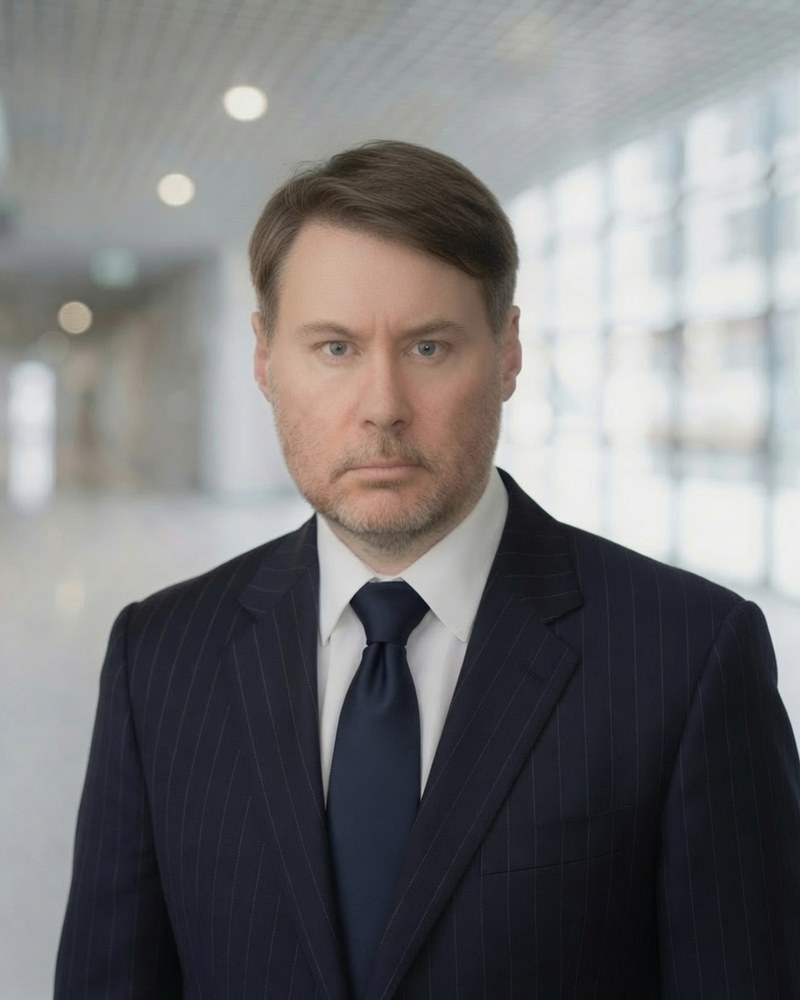
An earnout dispute is where the deal becomes a case. Eli Albrecht has structured and negotiated M&A transactions across hundreds of closings. Brian C. Kerr litigates business disputes in Delaware's Court of Chancery, Superior Court, and Supreme Court, and in state and federal courts nationwide. We know which provisions buyers rely on – and where they give.
Fees: fixed, contingency, or hybrid
- Fixed fee – for defined phases: reviewing the agreement and the numbers, the objection notice, an accountant proceeding, or negotiation.
- Contingency – where the claim, the damages, and the buyer's ability to pay support it, we take the earnout claim for a share of the recovery. Depending on how the case underwrites, we may also pay the costs of the case.
- Hybrid – a reduced fixed fee combined with a share of the recovery.
Many engagements start with a fixed-fee earnout review – the agreement, the statement, and the numbers – and then move to the structure that fits the claim. Fee terms, including who bears costs and when, are set out in writing in the engagement letter before work begins. How we take cases on contingency.
Common questions
Can a buyer reduce my earnout by changing how the business is run?
It depends on the purchase agreement. Some agreements require the buyer to run the business consistently with past practice, to use specified efforts to reach the targets, or not to act to avoid the earnout; others give the buyer broad discretion. Where the agreement is silent, the implied covenant of good faith may limit conduct aimed at defeating the payment, though courts apply it narrowly. The answer starts with the words of the agreement, and we read them first.
My agreement sends disputes to an independent accountant. What does that mean for me?
Many purchase agreements send disputes over how the earnout was calculated to an independent accountant, whose decision is usually final on the questions it is allowed to decide. Claims about how the buyer ran the business, bad faith, or fraud often fall outside that process and belong in court or arbitration. Which claims go where – and in what order – is one of the first questions we answer.
I just received an earnout statement I disagree with. What should I do first?
Find the objection deadline in the purchase agreement and calendar it; the window is often short. Keep every document and communication about the business's performance. Don't sign a release or an amendment without advice. Then talk to us – ideally well before the deadline, so the objection can be specific.
Do you take earnout claims on contingency?
Yes, when the claim, the damages, and the buyer's ability to pay support it. We also take earnout claims on a fixed fee or a hybrid – a reduced fixed fee combined with a share of the recovery. Depending on how the case underwrites, we may pay the costs of the case. Terms are set out in writing in the engagement letter.
I was terminated after the sale. Can I still pursue the earnout?
Termination does not necessarily end the earnout. Some agreements protect or accelerate the payment when a founder is terminated without cause, and a termination that cuts the founder off from the business can bear on claims about how it was run. The purchase agreement and the employment agreement have to be read together; we do.
I still work for the buyer. Can we talk confidentially?
Yes. What you tell us is kept confidential. Many founders still work for the buyer when an earnout dispute begins; we will discuss how to protect the claim – and your position – while you do.
The earnout is part of the price. Collect it.
Request an earnout review →